Financing Built for Commercial Construction Projects
Finance eligible construction projects for business use, investment, development, or resale with support from a local commercial lending team at First Hope Bank.
Financing Structured Around Your Construction Project
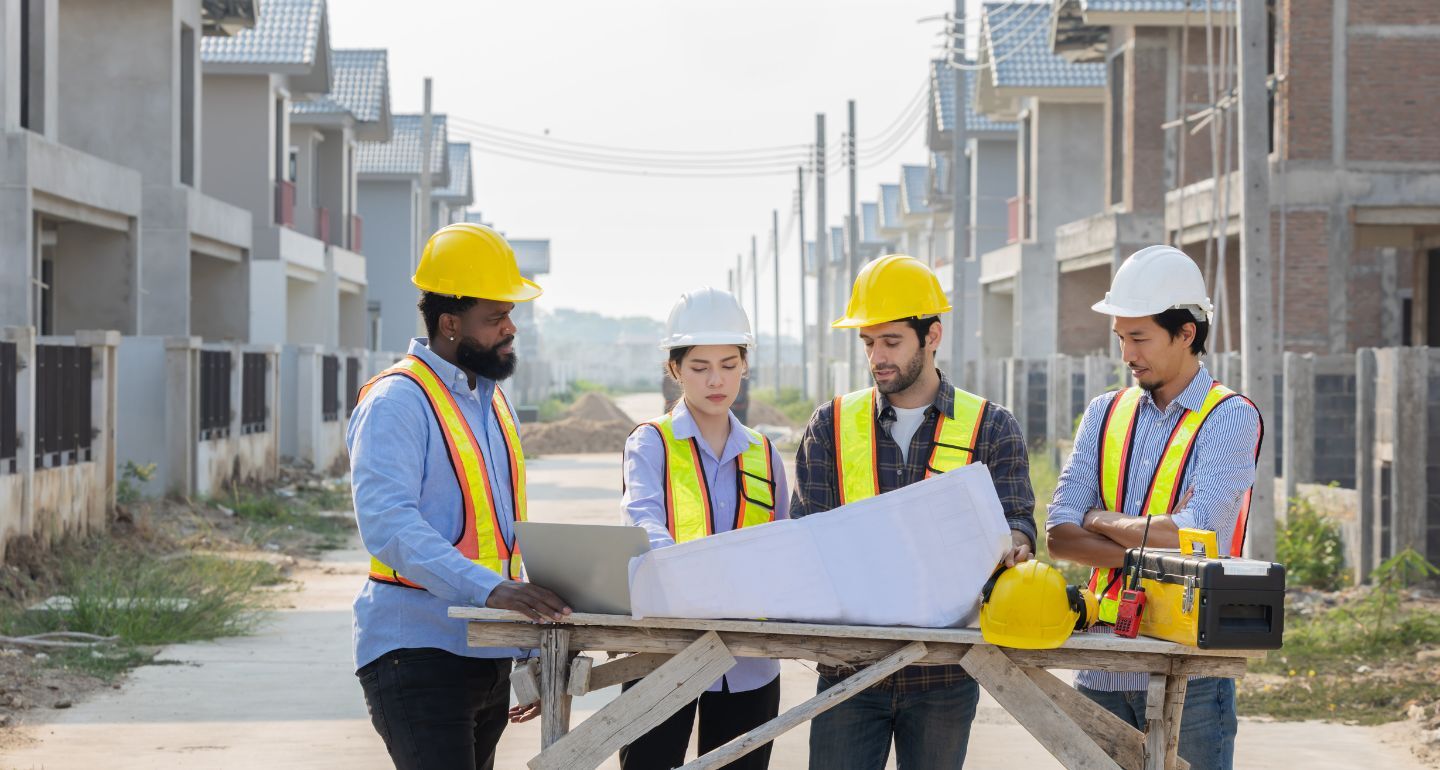
First Hope Bank commercial construction loans can support eligible projects from property purchase through construction, with financing and draw requirements based on the scope of the project.

Financing for Developers and Businesses
Commercial construction financing may be available for developers, businesses, and owner-occupants completing eligible projects for business use, investment, development, or resale.

Support for a Range of Construction Projects
Eligible projects may include single-family, 1-4 family, multifamily, and certain commercial construction when the purpose is business use, investment, development, or resale.

Borrower Equity at the Start of the Project
For a property purchase, a common structure is a 50% borrower down payment with First Hope Bank financing the remaining 50%, subject to the individual request and credit approval.
Funds Released as Work Is Completed
Construction draws are funded on an as-complete basis after completed work is verified and required title work is obtained.
Engineer Verification Before Funding
When a draw is requested, the Bank engineer verifies completed work and provides a report before the draw is funded.
Project and Financial Information Required
The review typically includes borrower financial information plus project costs, plans or build details, contracts, approvals, and proposed sale or lease information when applicable.
Commercial Construction Lending With Local Support
Work with a local commercial lending team that can guide you through the financing structure, project review, construction draw process, and next steps from application through completion.
Work Directly With a Commercial Lender
Discuss your project, financing needs, timeline, and required documentation with a First Hope Bank commercial lender who can help guide the process.
Banking Tools to Support Your Business
Pair commercial lending support with First Hope Bank business checking, online and mobile banking, and treasury management tools for day-to-day business needs.
Easy Steps to Explore a Commercial Construction Loan
Start with a conversation about your project, then work with First Hope Bank through documentation, credit review, appraisal, and closing.
Discuss Your Project and Financing Needs
Talk with a First Hope Bank commercial lender about the property, project scope, intended use, costs, timeline, and financing request.
Submit the Project and Financial Package
Provide the requested tax returns, personal financial statement, liquidity and other financial information, hard and soft cost breakdown, build description, contract, approvals, and proposed sale or lease figures when applicable.
Complete Review, Appraisal, and Closing
After credit approval, the Bank proceeds with the appraisal and closing process. Once construction is underway, draws are funded as completed work is verified and title requirements are satisfied.
Manage Your Business Banking Wherever Work Takes You
First Hope Bank Business Online & Mobile Banking helps you manage accounts, transfer funds, receive alerts, pay bills, find locations, and access banking tools from your browser or mobile device.